Employer due diligence is the research a candidate does on whether a company will still exist in two years, and almost nobody does it. A restructure, a bankruptcy and a mass layoff later, I run a fixed set of checks before I apply: filings, funding history and its date, headcount direction, review patterns, and a handful of interview questions that don’t sound like an audit. The surprise was that only one of my three endings was financial, and the other two came from politics and strategy, so the checks worth the most time are the ones that read how a company makes decisions. None of it makes you safe; what it gives you is a risk you chose instead of one you discovered.
Three companies, three endings: a climate tech SaaS company where I ran the content function solo, ended by restructuring; a B2B eMobility company, ended by an insolvency I found out about from a Teams recording; and a B2B SaaS company serving 200+ higher education institutions, ended by a mass layoff.
I did almost no employer due diligence before any of them: I researched the role, the product and the interviewer, and treated the company’s continued existence as a given.
Which is a strange asymmetry once you look straight at it: they run background checks, reference calls and four rounds of interviews on you, and you get a careers page and a founder who seems excited. Employer due diligence is the missing half of that exchange.
What can you check before applying?
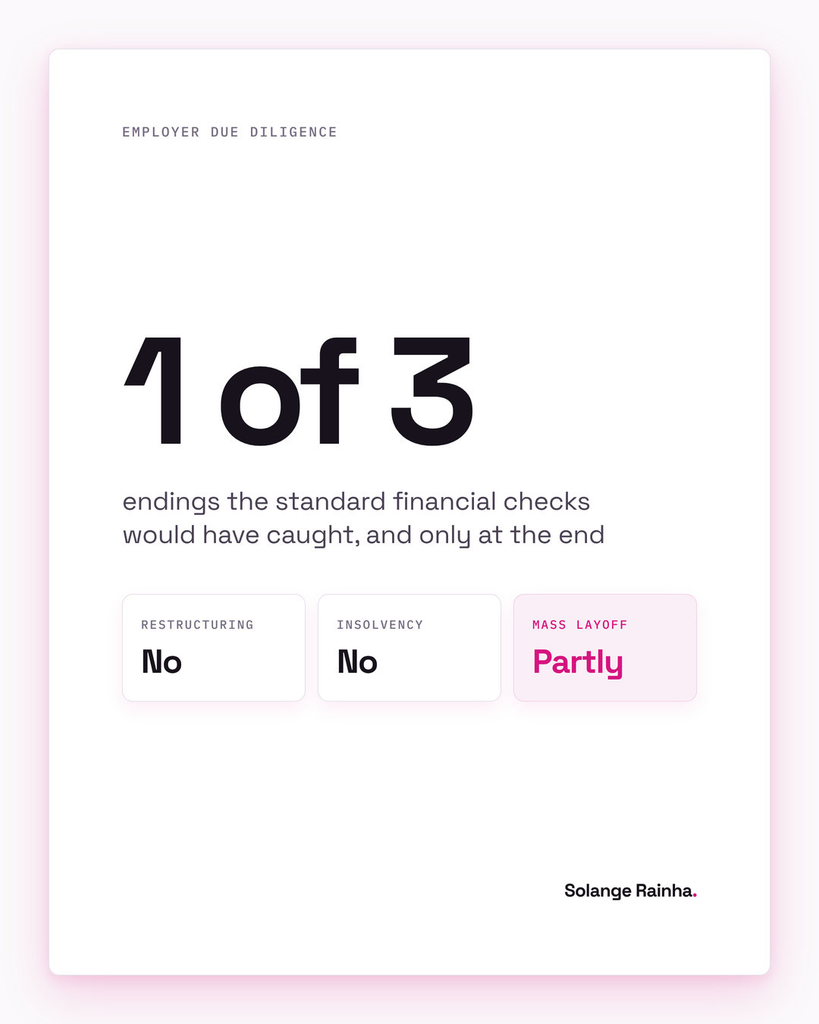
More than most people think, and in Europe more than the American advice suggests, because most of that advice points at SEC filings that private European companies never produce. Employer due diligence over here runs on registry data.
Start with the filings. In Portugal the Ministry of Justice publishes corporate acts for free, annual accounts sit with the commercial registry, and the Bank of Portugal publishes financial data on companies too (a decent overview of the public sources is here). Citius, the courts portal, publishes insolvency proceedings, revitalisation processes (PER) and a public list of enforcement proceedings where no assets were found to settle a debt, all searchable by tax number, which gets around the problem of three companies sharing a name. For UK entities, Companies House gives you filing history, accounts and any insolvency record, also free.
Funding next, where the date tells you more than the amount. A Series A raised 40 months ago at a company that’s still hiring is a completely different proposition from the same round raised eight months ago, and Crunchbase or Dealroom will tell you which one you’re looking at in about a minute.
Headcount is where people take the snapshot and stop, and the snapshot is the useless part. LinkedIn’s company insights (a Premium feature) show employee count over time, so read the direction over 12 months and read where the change sits: marketing and support shrinking while engineering holds steady tells a different story from everything declining together. Watch the top of the building too: a UK recruitment firm’s guide to spotting a shaky employer lists sudden leadership departures among the obvious warning signs, alongside hiring freezes and benefits quietly getting worse.
Reviews are worth reading for the pattern, because the rating tells you almost nothing. Several in one quarter mentioning restructuring, or late payments, or a department that stopped existing, is a finding.
Last, client concentration, as far as you can see it from case studies, logos and press coverage. A B2B company whose public proof rests on three named clients carries a specific risk, and losing a major client is exactly what came right before the eMobility company went under.
What ended my last three jobs?
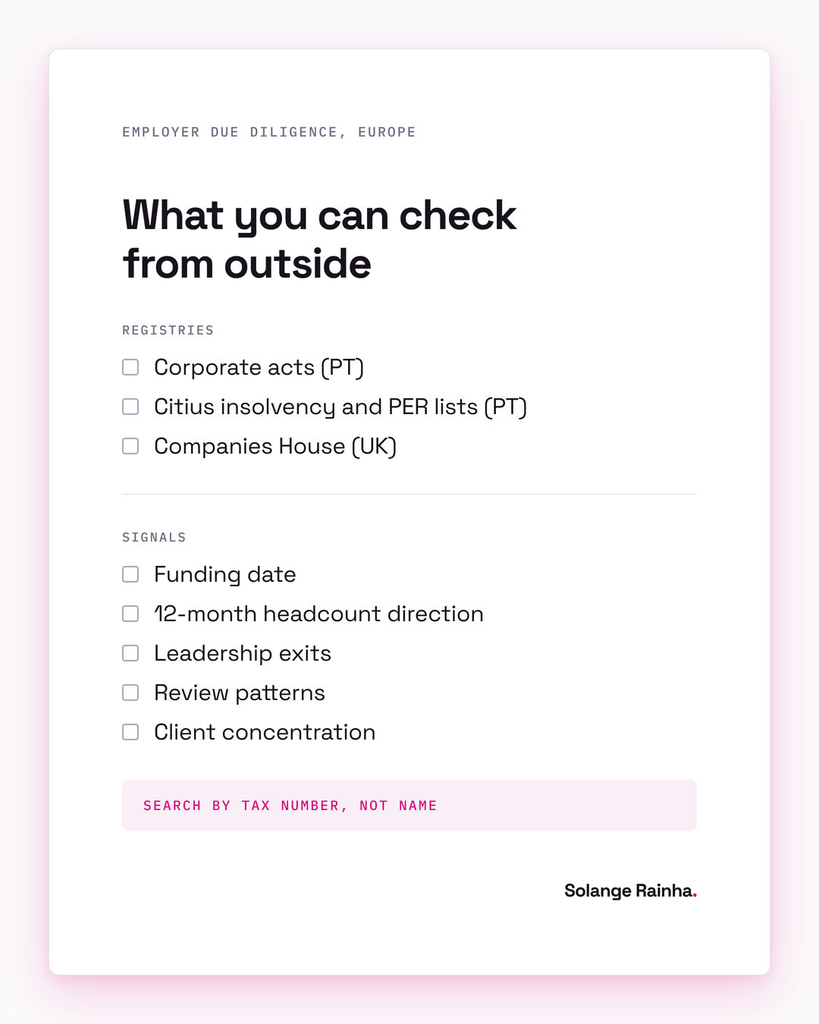
Only one of them was a financial failure, and it took all three to see it.
| What ended it | What caused it | Would financial checks have caught it? |
|---|---|---|
| Restructuring | A breakdown between marketing leadership and the executive team. The marketing team was dissolved and rebuilt around who company leadership wanted to keep. | No. The balance sheet had nothing to do with it. |
| Insolvency | A major client lost, communicated with the reassurance that finances were stable, two weeks before announcing bankruptcy. | No. Not public, not in any review, not known to my own manager. |
| Mass layoff | A year of repeated positioning changes with the marketing team’s evidence not moving decisions, then a mass layoff framed as survival by the time it was announced. | Partly. The layoff had set in by the end, but the cause was how decisions got made. |
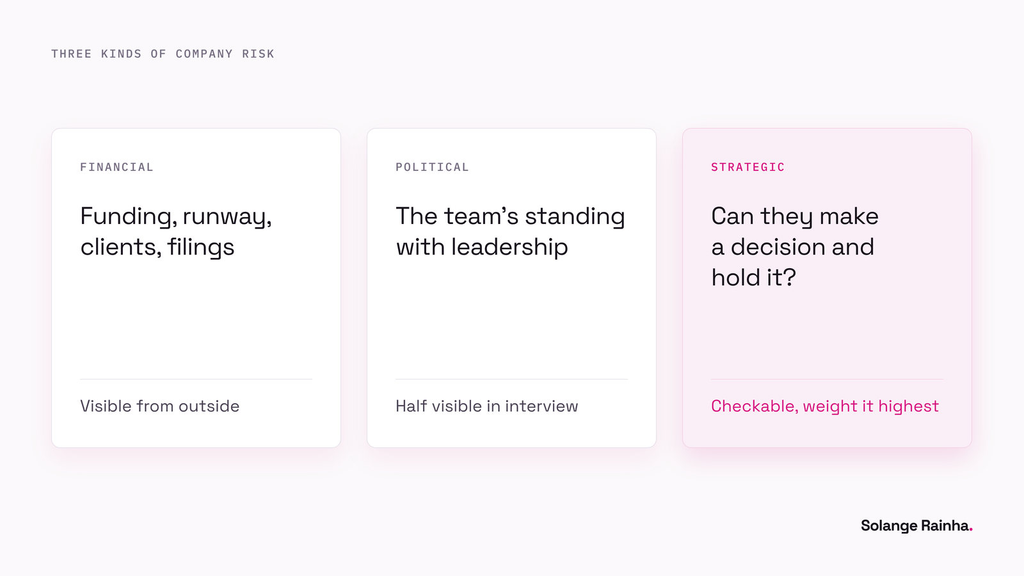
So the scorecard on employer due diligence as it’s usually described is one out of three, and that one only in the final months. Company risk comes in more than one kind, and the standard financial checks read just the first of these:
- Financial risk is the one every guide covers: funding, runway, client concentration, filings. Worth checking, and the least likely to be what gets you.
- Political risk is whether the team you’re joining has a stable relationship with the people above it. A restructure that dissolves a department is often about a relationship, not a budget, and the department is the collateral. You can’t see it from outside, though you can half see it in an interview if you ask the right questions.
- Strategic risk is whether the company can make a decision and then hold it. Repeated repositioning, evidence that changes nobody’s mind, a function hired to be listened to and then ignored: it degrades a business slowly, and by the time it shows up in the accounts the cause is a year old. I’d weight this one highest now, because it does the most damage and it’s also the easiest to check.
The pivot at the higher education SaaS company is written up from the content side in rebuilding a content strategy after an ICP pivot, and the insolvency, the Teams recording and what I said about it afterwards are in short tenure on a CV.
How do you check political and strategic risk?
Through the company’s history and its turnover, because neither shows up in a filing, but neither is invisible either.
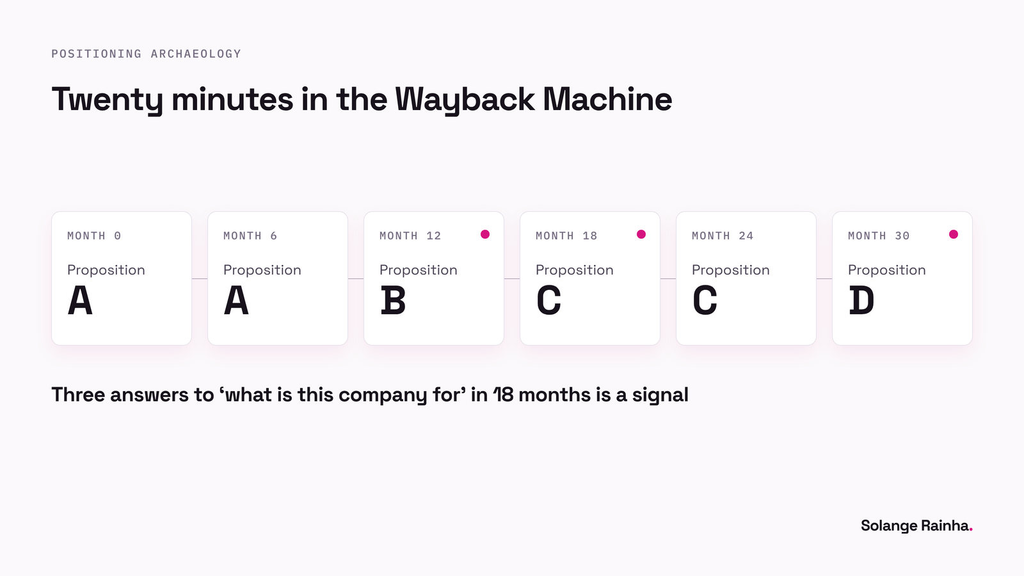
Positioning archaeology first: run the homepage through the Wayback Machine at six-month intervals for two or three years and count how many times the core proposition changed, and whether each change builds on the last or replaces it. Three different answers to “what is this company for” inside eighteen months is a strategic risk signal, and it costs you twenty minutes.
Do the same with turnover, but by function instead of company-wide. LinkedIn shows who left and when, and a marketing team where nobody has passed 18 months, sitting next to engineering tenure that looks completely normal, is telling you something quite specific about where that function sits.
Two smaller checks round it out. The first is how long the head of the team has been in post, and whether they report to the CEO or through somebody else, because a team two levels from the decision-maker has less ability to change a decision, which hurts if changing decisions is what you’re being hired for. The second is whether the team exists yet at all: being the first proper marketing team somewhere is an opportunity and a risk in the same package, since you arrive with no established credibility and no track record of having been right, in front of people who’ve run the company on instinct so far. (I wrote about that first stretch in a content function’s first 90 days.)
How do you ask about stability without sounding like an auditor?
You ask questions a confident company enjoys answering. Every one of these reads as commercial interest rather than suspicion, and the discomfort in the answer tells you more than the answer does. Y Combinator gives candidates the same advice in plainer words:
“Ask about the company’s runway, burn rate and plans for future funding.” (Ryan Choi, Y Combinator)
| Question | What it sounds like | What you’re reading |
|---|---|---|
| “How is the company funded, and where are you in that cycle?” | Normal candidate curiosity | Whether they answer plainly or deflect. |
| “What does revenue concentration look like? Are you dependent on a few large accounts?” | Commercial literacy | Client concentration risk, and whether they’ve thought about it. |
| “How has headcount changed over the past year, and what’s the plan for the next one?” | Interest in team growth | Contraction they’d rather not mention. |
| “What would have to be true in 12 months for this hire to be considered a success?” | Ambition and expectations | Whether anyone has a 12-month plan at all. |
| “When did this function last change leadership’s mind about something?” | Interest in influence and autonomy | Whether evidence moves decisions here, or decorates them. |
| “How has the positioning evolved over the last two years?” | Wanting context on the story | Whether they describe a direction or a series of restarts. |
Two rules on delivery: ask them of more than one person, because inconsistent answers are the finding, and ask late, once they want you.
The answers that worry me contain no figures. “We’re doing really well,” from somebody who could have said “we’re profitable” or “we closed the round in March,” is a choice.
What should rule a company out?
A short list, because a long one leaves you applying nowhere.
Any delay in paying people comes first, whether it’s salaries, contractors or suppliers. It shows up in reviews and it’s the last signal before the end, never an early one. Then an insolvency or revitalisation proceeding sitting on the public record with no explanation offered when you ask, and two or more of the standard distress signals stacked together: recent layoffs, plus a hiring freeze this role has somehow escaped, plus people leaving the executive team.
The other three are softer to spot and just as final. A role that exists to fix a problem nobody will describe, where nobody can tell you what happened to the last person or why the function has no strategy (the answer to both is usually financial). Evasion on the funding question, which is different from a bad answer, since a bad answer is workable. And a team that has never changed a decision, because if nobody can name a time the team you’d be joining persuaded leadership of anything, you’re being hired to produce evidence for decisions that have already been made.
How do you weigh stability against a role you want?
You price the risk. Stability isn’t the only quality worth having, and pretending otherwise gets you a career of safe, boring jobs at companies that restructure anyway.
A riskier company has to pay more, in money or in scope: the chance to build from nothing, ownership I wouldn’t get elsewhere, work worth a portfolio whatever happens to the company afterwards. The eMobility role gave me two product launches and a social presence rebuilt from a standing start, which I wrote up in the social turnaround piece, and the climate tech role gave me a solo content function producing 60+ pieces over 18 months.
The other half of pricing risk is what you do once you’re inside: document your own work as you go, because when a company folds the evidence goes with it: the site comes down, analytics access ends, colleagues scatter across four countries. And know what you’d do if the announcement came tomorrow, which is a fifteen-minute exercise I’d have benefited from three separate times and never once did.
What can’t employer due diligence tell you?
Whether the founders are about to fall out, whether the biggest client is renewing, whether the funding conversation that looked routine in March quietly stopped in June, or whether the people telling you the finances are stable believe it themselves, which in my case they did. Employer due diligence reads the outside of a company, and the decision that ends your job is usually taken by four people who aren’t talking to candidates.
Failure reaches funded, well-staffed companies with traction now, too. Carta counted 966 US startups on its platform shutting down in 2024, up 25.6% on 2023, after a first quarter in which 254 went out of business, the decade’s highest quarterly total so far.
So what the checks buy you is a risk profile: knowing a company leans on a few large clients, or that it has repositioned three times in two years, doesn’t tell you it’s going to fail, but it does tell you what to weigh against the offer, what to ask before you sign, and how much contingency planning belongs in your first month instead of your twelfth.
Candidates carry the burden of proving they’re worth the risk while having almost no ability to assess the risk they’re taking, and that asymmetry is structural. I’ve written it up more fully in what candidates can and can’t research, and covered how the resulting gaps get read in handling a career break on a CV. It took me a while to stop reading three company endings as a verdict on my own work, too, which is part of why the receipts don’t cure imposter syndrome.
Safety isn’t on offer, so what this buys is the difference between choosing a risk and discovering one, and the professional response to a risk you chose is to do the work properly anyway, which I’ve argued in why doing your job well was never quiet quitting.
Frequently asked questions
Employer due diligence is the research a candidate runs on a company’s financial health, funding, headcount trend, legal record and decision-making before applying or accepting an offer, in the same spirit that companies research candidates. It’s worth doing because job loss through company failure is common and mostly invisible from inside: Carta counted 966 US startup shutdowns on its platform in 2024, up 25.6%, and by the time distress is obvious to employees the decisions have usually been taken. The realistic goal is a risk profile you can weigh against the offer, since no amount of checking guarantees the company survives.
Most guidance assumes US public companies and SEC filings, which don’t apply. In Portugal, the Ministry of Justice publishes corporate acts for free, annual accounts sit with the commercial registry, and the Citius courts portal publishes insolvency and revitalisation proceedings plus a public list of enforcement proceedings with no assets found, all searchable by tax number. In the UK, Companies House provides filing history and accounts at no cost. Beyond filings, funding history and its date, 12-month headcount direction, executive turnover and patterns in recent employee reviews are the practical signals.
Ask how the company is funded and where it sits in that cycle, what revenue concentration looks like, how headcount has changed over the past year and what’s planned for the next, and what would have to be true in 12 months for the hire to be a success. Each reads as commercial interest and not suspicion, and the useful signal is often the delivery: a confident company answers with specifics, while deflection and answers with no figures in them are the finding. Ask the same questions of more than one person, since inconsistency tells you more than any single response.
Only partly. Financial checks can flag runway and client concentration problems, but restructurings often come from a breakdown between a team and its leadership, and layoffs from a company that can’t hold a strategic decision, neither of which shows up in a filing. The best proxies are homepage history in the Wayback Machine, turnover by function on LinkedIn, and asking when the team you’d join last changed leadership’s mind.